When buying a home in Canada, one step can quietly decide whether your deal moves forward or falls apart:
The home appraisal.
Many buyers only learn about it when there’s a problem. Here’s a clear, simple explanation.
What Is a Home Appraisal?
A home appraisal is a professional estimate of a property’s market value.
It is ordered by your lender, not by you.
In Canada, lenders like RBC, TD Canada Trust, Scotiabank and others require an appraisal to confirm the property is worth what you agreed to pay.
The bank wants to ensure:
The purchase price matches market value
The property supports the mortgage amount
Their risk is protected
Why an Appraisal Can Make or Break a Deal
If the appraisal matches the purchase price → ✔ Deal continues.
If the appraisal comes in lower than the purchase price → ⚠ Problem.
Example:
You agreed to buy a home for $800,000
The appraisal comes back at $770,000
The bank will only finance based on $770,000, not $800,000.
Now the buyer must:
Pay the $30,000 difference out of pocket
Renegotiate the price
Or walk away (if financing conditions allow)
This is why appraisal issues scare buyers.
Real-Life Example (Common Scenario in Canada)
In competitive markets, buyers sometimes offer above asking.
Let’s say:
Asking price: $749,000
Winning offer: $810,000
Appraised value: $785,000
Now the buyer must cover a $25,000 gap.
If they don’t have extra funds available, the deal may collapse.
This happens more often in:
Multiple-offer situations
Rapidly rising markets
Unique or over-renovated properties
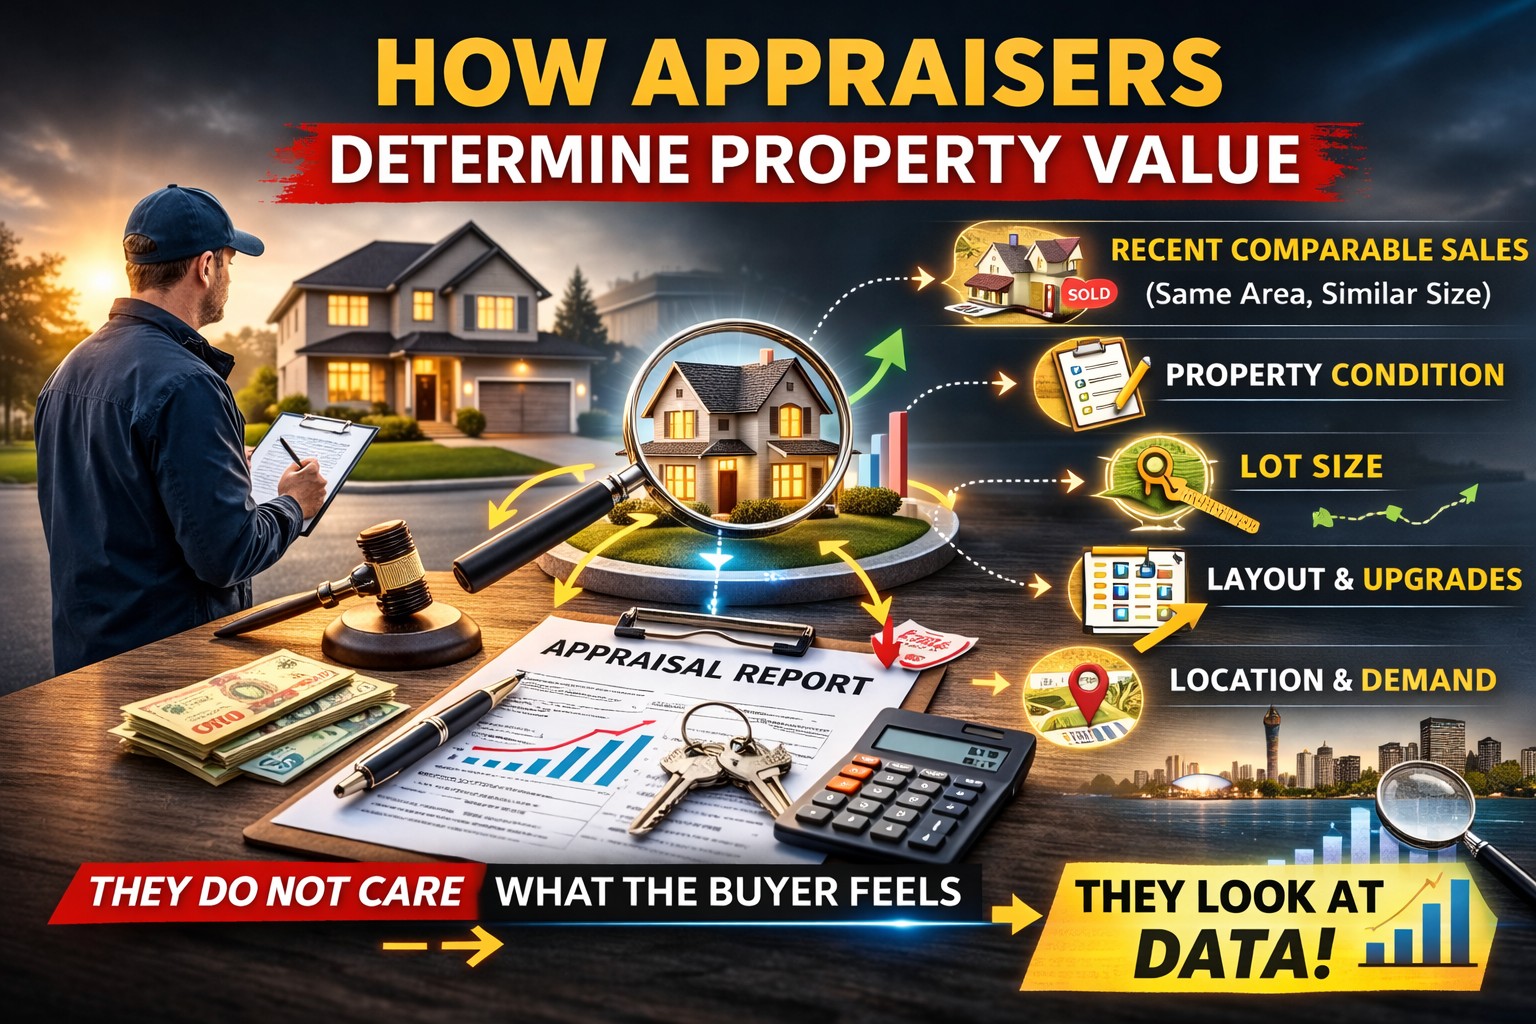
How Appraisers Determine Value
Appraisers review:
Recent comparable sales (same area, similar size)
Property condition
Lot size
Layout and upgrades
Location and demand
They do not care what the buyer emotionally feels.
They look at data.
How to Protect Yourself
Include a financing condition when possible
Avoid emotional overbidding
Work with an experienced agent who understands comparables
Get pre-approved properly
Keep extra liquidity if bidding aggressively
Understanding how a home appraisal works in Canada can protect you from unexpected surprises. Before making an offer, know your numbers, understand comparables, and plan for possible valuation gaps.
If you want help reviewing a property before you offer, reach out — it’s better to analyze before signing than fix problems after.
Disclaimer:
This article is provided for general informational purposes only and does not constitute legal, financial, or real estate advice. Market conditions, pricing, and project details may change without notice. Always conduct independent due diligence and consult licensed professionals before making purchasing decisions.
Aman Khattra is a licensed real estate agent with Royal LePage Platinum Realty. This content is intended for educational purposes only.

